


The announcement that India has signed a trade agreement with the EU is the kind of good news the beleaguered wine industry needs right now.
Nobody really has any clear idea of where the Indian wine market is heading, or at what speed. But those with money to splash around on supposedly authoritative reports can take their pick between Euromonitor’s prediction of 12% compound annual growth, IMARC’s 16.3% and Technavio’s 23.8%
If IMARC is correct, by 2033, the market will be worth $892 million. Grand View Research favours a much more optimistic $2.66 billion.
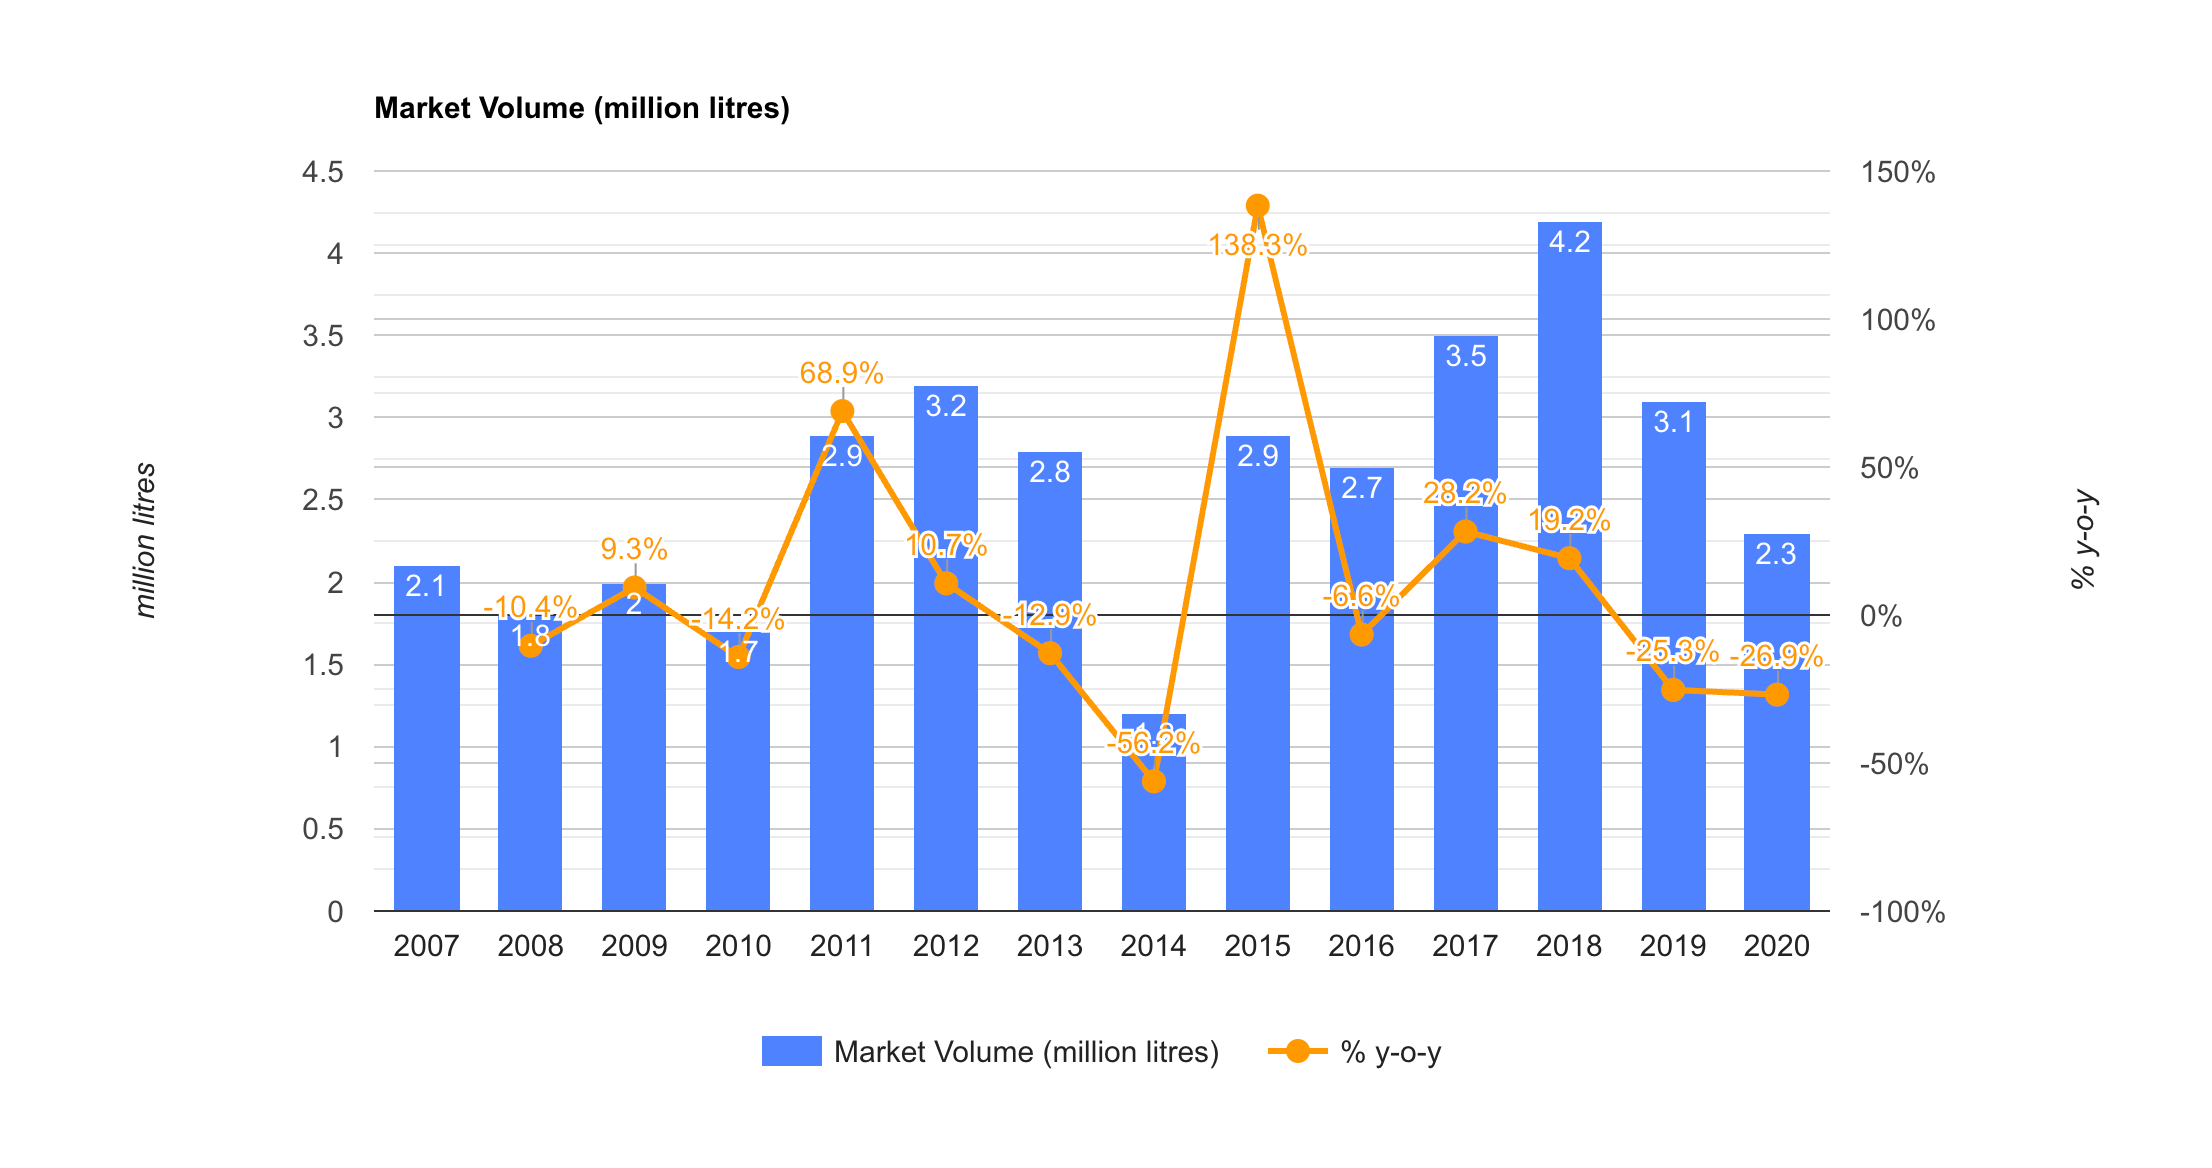
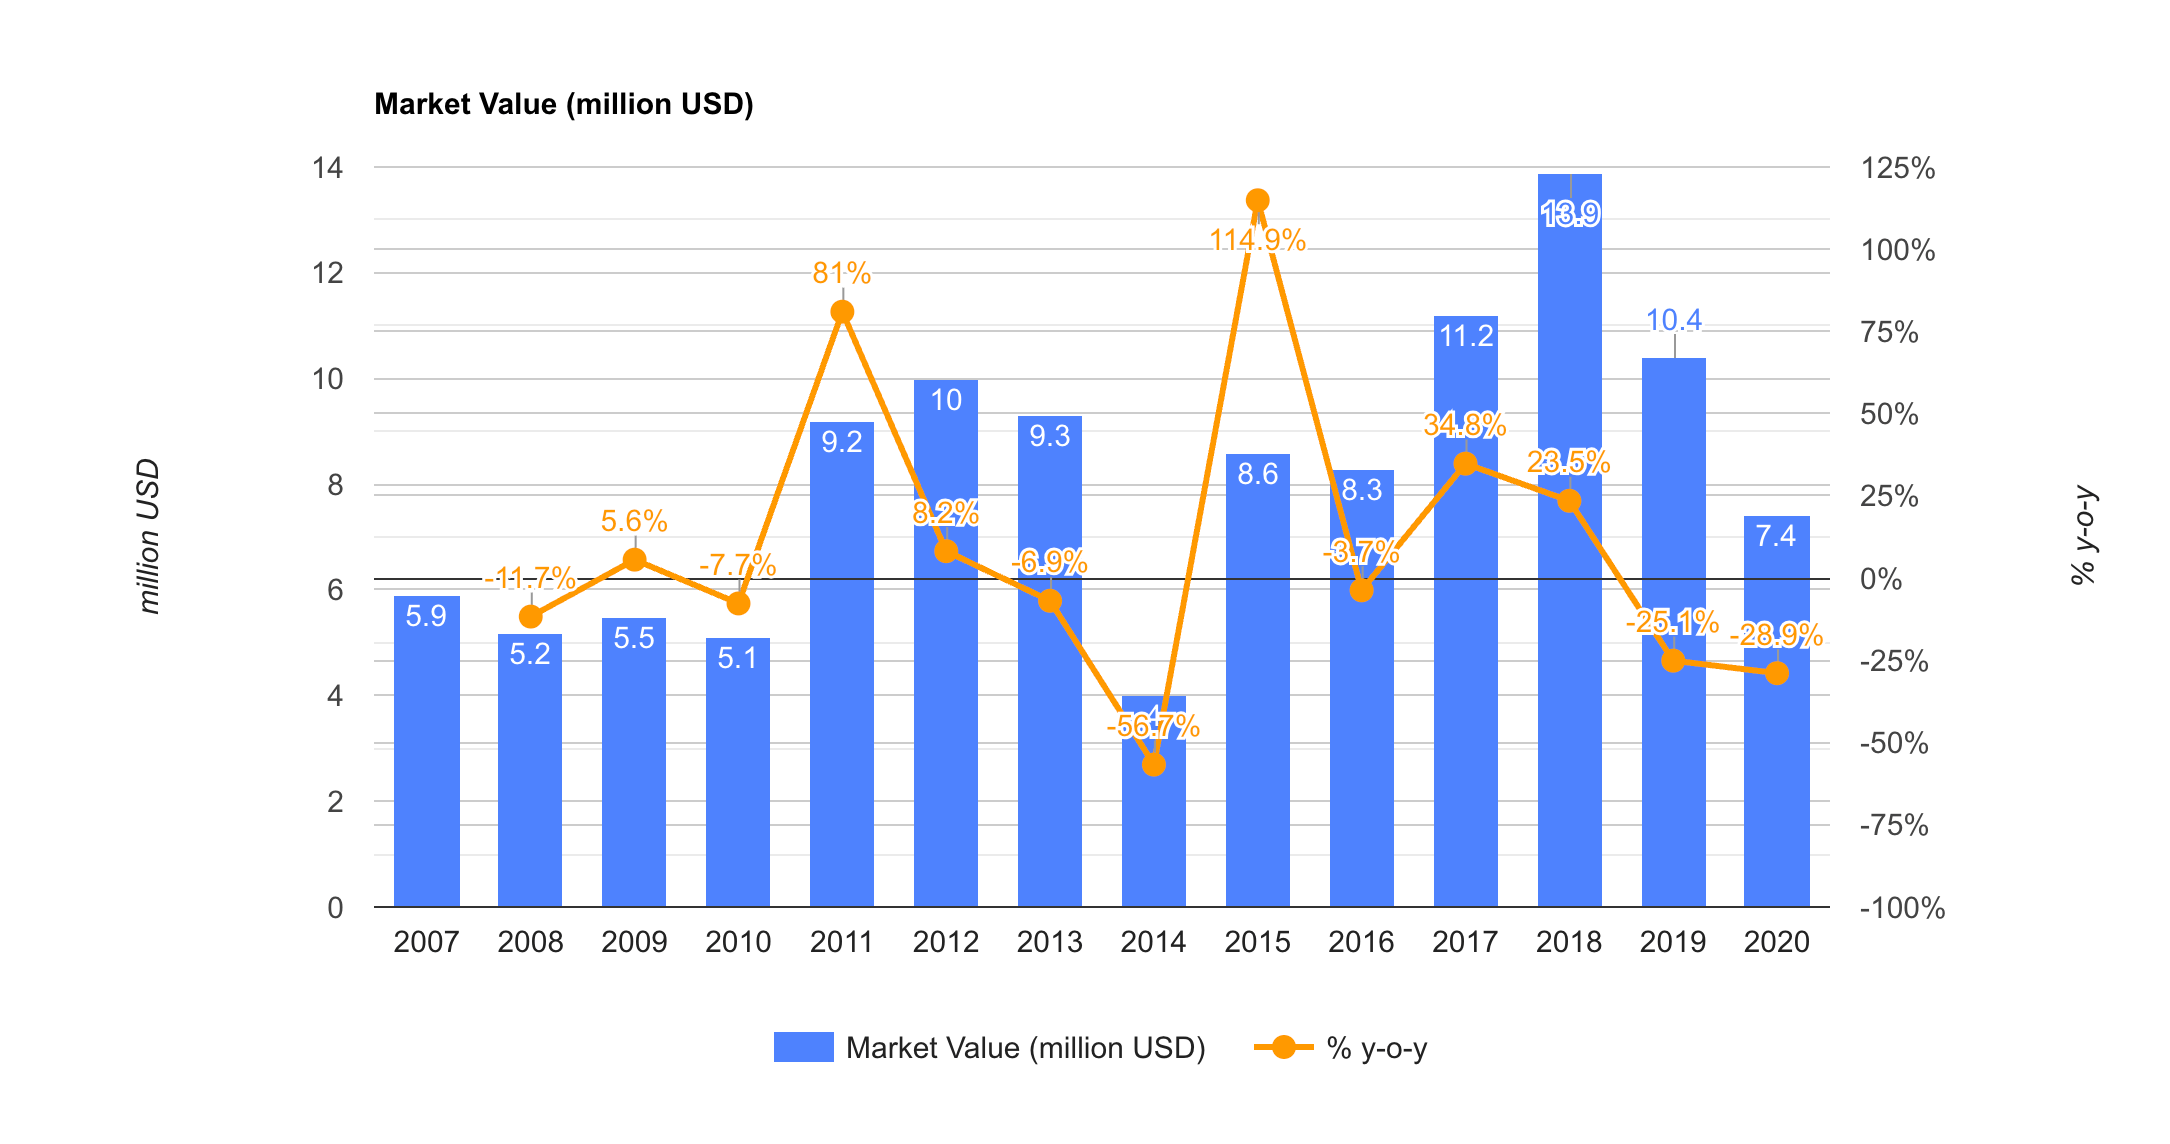
Unfortunately, all these rosy prospects need to be viewed alongside the fact that the
market actually shrank in 2024 and declined by a further 5-8% last year. Consider the volatile performance prior to 2020 and, even if/when sales stop falling, you have to wonder whether steady growth at any rate is really likely.
Alcohol fans
Interestingly, despite all of its major religions taking a more or less negative view of alcohol, and Article 47 of the Indian Constitution still stating “the State shall endeavour to bring about prohibition of the consumption except for medicinal purposes of intoxicating drinks and of drugs which are injurious to health”, Indians consume 4.9 litres of pure alcohol per person per year. This puts them at 97th on the world rankings, not much lower than the Chinese (87th with 5.7 litres, ) and pretty much in line with the wine-producing Armenians (94th) and North Macedonians (98th).
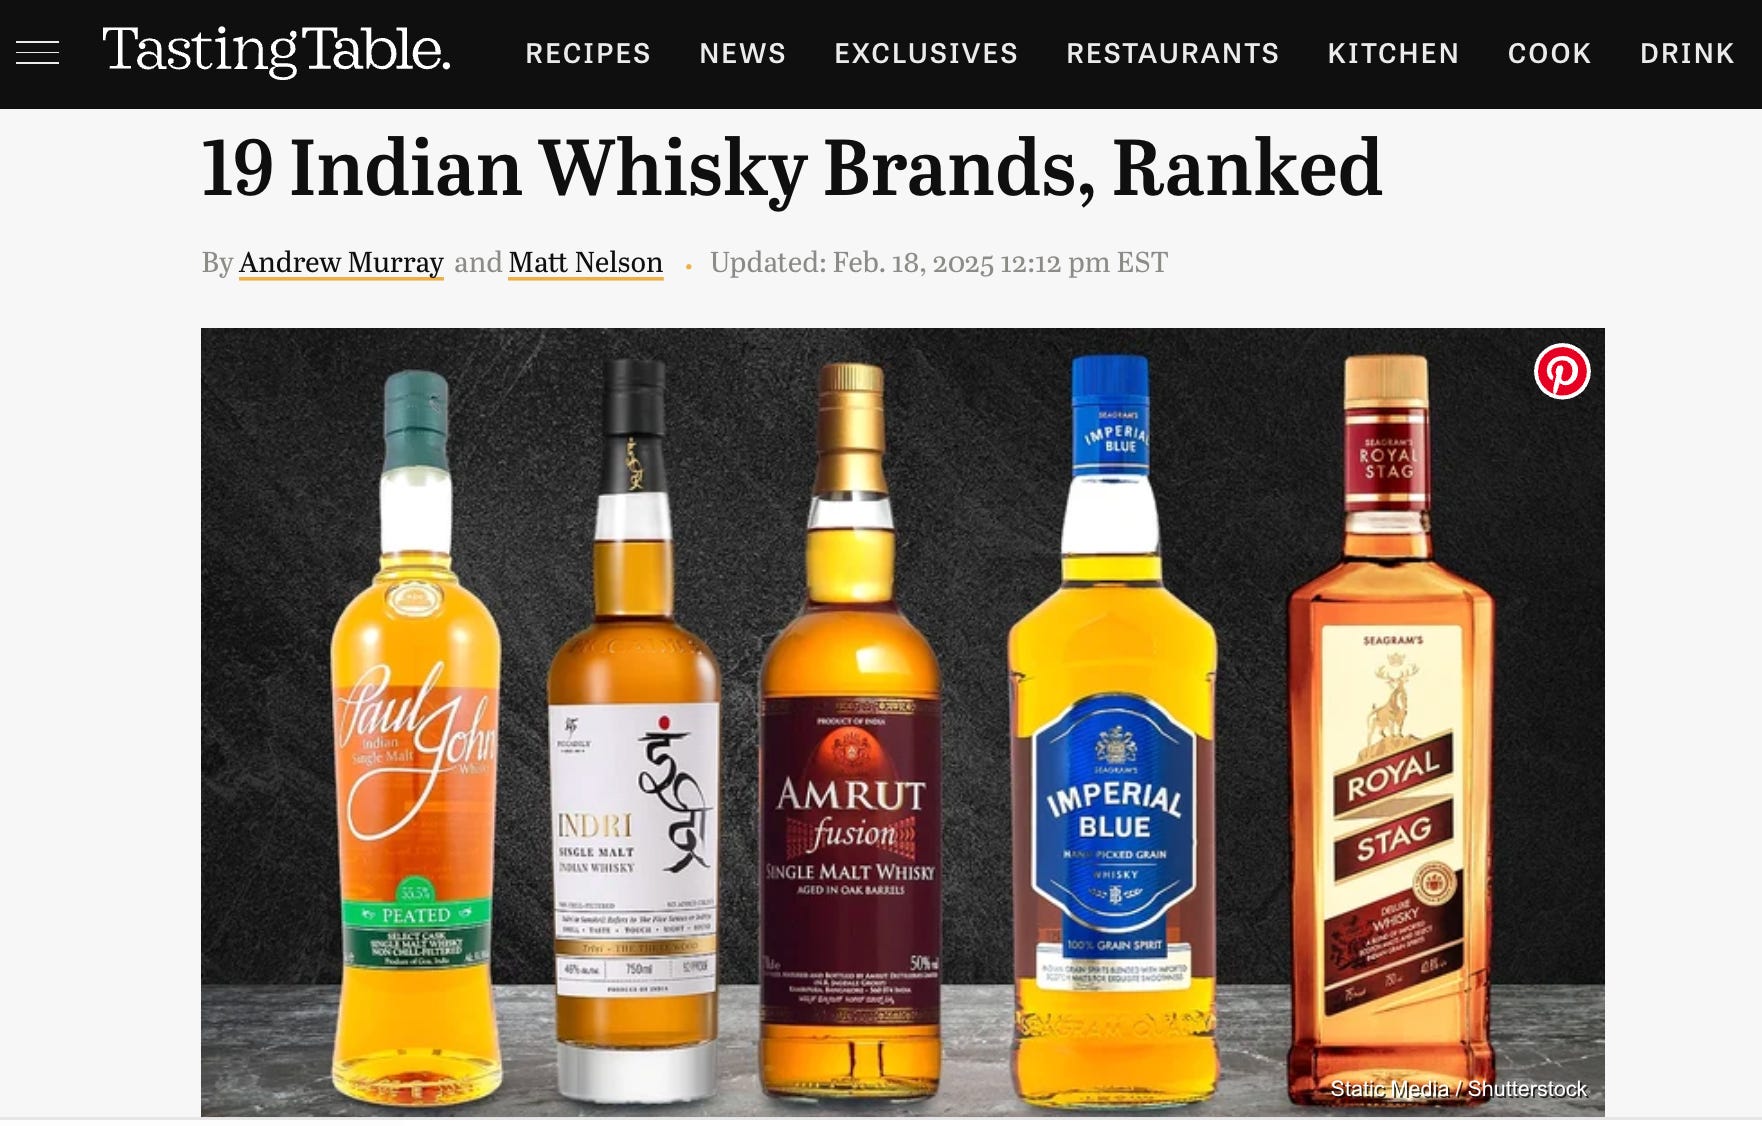
But, and this is a big ‘but’, very little of alcohol enjoyed by Indians comes in the form of wine. In 2024, a report by The Times of India and The Hindu Business Line revealed that whisky is not only India’s favourite tipple; it represents over 60% of all alcoholic consumption. India is the biggest export market for scotch whisky and, again in 2024, exports of its domestically-produced whisky brought in $78.5 million.
Strikingly, whisky’s share of the Indian alcohol market is very close to Baiujiu’s share in China, but of course, the Chinese spirit is far less relevant to export and import figures.
Other spirits, especially rum, are popular in India, and so is beer. Wine consumption, however, is estimated at just 0.03 litres to 0.04 litres per capita. At the peak of its wine boom, the Chinese managed to buy 1.34 litres per person, though it is unclear whether this figure reflects the amount actually consumed. It has, in any case, tumbled to 0.6 litres, but that’s still 15-20 times more than India.
In 2023, India imported 7.8m litres of wine compared to Vietnam’s 23m, and the 26m Thailand shipped in during 2022. To put these figures in context, China imported 114 million litres in the first half of 2025, despite a 12.5% decline from the previous year.
Of course, tortoises can beat hares, but when it comes to a wine drinking contest between the two most populous nations on the planet, it’s going to have to be a very long race.
The new trade deal will help - but not as dramatically, nor as quickly as some suppose. India’s swingeing 150% import duties on wines will, indeed, be reduced, but not on wines with a CIF price of under €2.50 per bottle.
As my friend, Rajeev Samant, head of Sula Wines and Indian importer of our le Grand Noir wines said in a press release,
“We believe this framework delivers a balanced outcome, as it protects over 90% of Indian wines, which retail at MRPs below ₹1,500 (€13.64) per bottle, while also supporting the long-term expansion of the domestic wine market.
Further, drawing parallels with the India–Australia FTA, where duty reductions were implemented gradually over a decade, we expect a similar phased approach for European wines, with the first duty reduction to ~75% expected after one year, gradually tapering to ~20% for premium wines and ~30% for mid-priced wines over a 7–10 year period.”
Samant’s reasoning behind this statement was to reassure investors in Sula, and others in the Indian wine industry that their market was not about to be flooded with bottles from Europe’s overflowing wine lake. He believes the agreement “adequately safeguards the interests of the Indian wine industry” and “remain[s] confident and expect[s] only a limited impact from the proposed agreement, largely confined to our [Sula’s] most-premium RASA range.”
It is also important to note that excise duty is not the only imposition wine faces in India. Distribution has to be handled on a state-by-state basis, with ‘label registration’ having to be paid for each wine, every year. There are also costs of wholesale licenses, excise band fees and 15-25% VAT, depending on the state.
Weak currency
Another factor that nobody is talking about in the context of the India-EU deal is last year’s 20% fall in the value of the rupee against the euro. European wines that were retailing at ₹1,600 or ₹1,700 (already above the ₹1,500 threshold) are now heading for ₹2,000 - a price that is beyond the means of many current wine drinkers. The rupee is expected to take a further dip over the next 12 months.
There is no question that the Indian economy is growing and that a middle class is emerging that could develop a taste for wine. But this was also true for China, which, for a while, looked as though it would become a leading market.
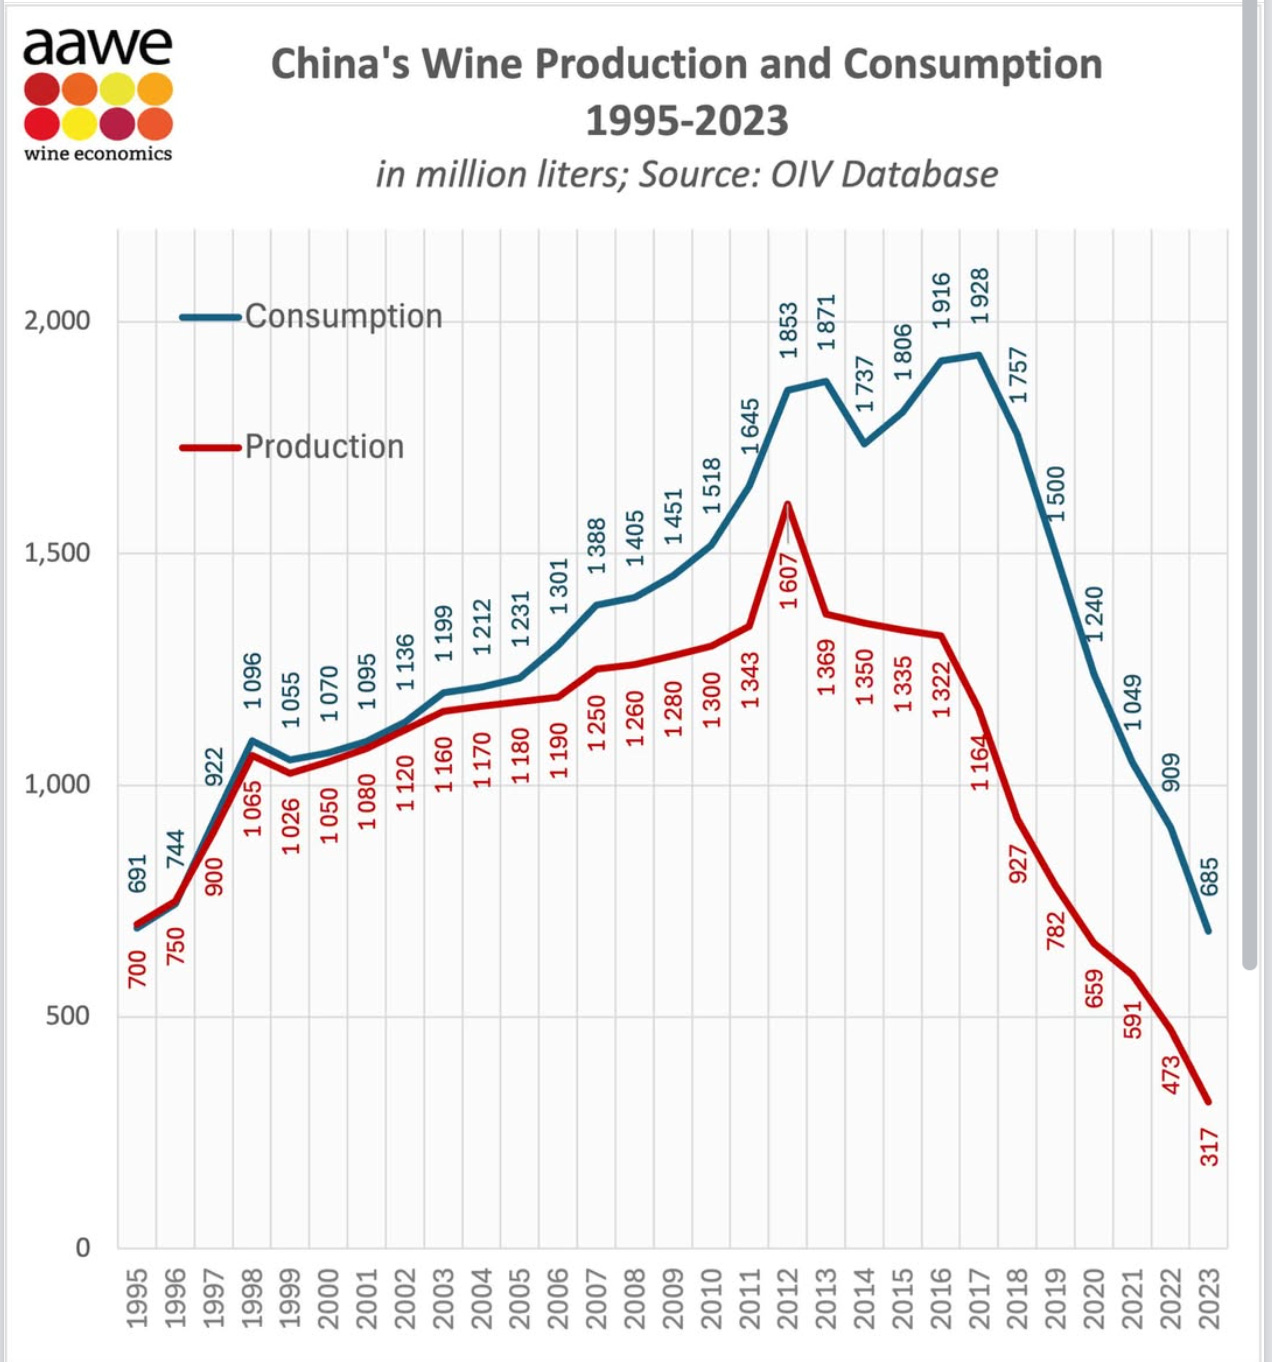
Indeed, it was shipments to China and projections of their continued growth that briefly distracted the ine industry from the decline in consumption almost everywhere else. But, as recent figures show, this was an illusion.
Despite the best efforts of wine producers across the globe and WSET educators, Chinese consumers clearly did not fall in love with the wine that suddenly found its way onto their TV screens and into their local supermarkets. They enjoyed gifting it for a while, and toasting with it at banquets, and some certainly did get a taste for it - but not nearly enough to stop consumption from falling back over the last seven years to where it was three decades ago.
Try it with food; that might make it taste better
Despite the assertions that this or that style wine was ‘perfect with Chinese cuisine’ - an absurd notion in any case - few people developed a need to open a bottle with their meals.
India, like China, has no cultural history of drinking wine, nor of needing to wash their food down with an alcoholic beverage. And perhaps this isn’t really so surprising.
The US is a highly developed nation that has welcomed large numbers of migrants from wine-drinking and -producing European nations. It has also created a huge wine industry of its own. Despite this, around three-quarters of the population has no desire to drink the stuff more than very occasionally if at all.
I’ve no idea what percentage of Chinese now ever drink wine, but my Indian friends estimate that the figure in their country is way below 1%. In a country where >% are considered to be middle class.
We have to ween ourselves off the delusion that wine drinking is any more of a default behaviour for anyone who can afford it, than going to classical music concerts.
Change of plans
On the basis that, if you go on doing what you do, you’ll get what you’ve always got, European and other wine producers focusing on India would be wise to avoid repeating the mistakes they made in China. Instead of focusing on dry red wine, they could start with off-dry, or even frankly sweet, white. These, after all, were the styles that helped convert the UK and Australia from beer to wine, and they’re the styles that are gaining traction in China right now.
And, to retun to one of my favourite themes, they could be inventive with packaging. If there’s very little logic why all wine from 5% ABV to 15% should be sold in 75cl bottles in Europe, there’s absolutely none for this size to be the default in India.
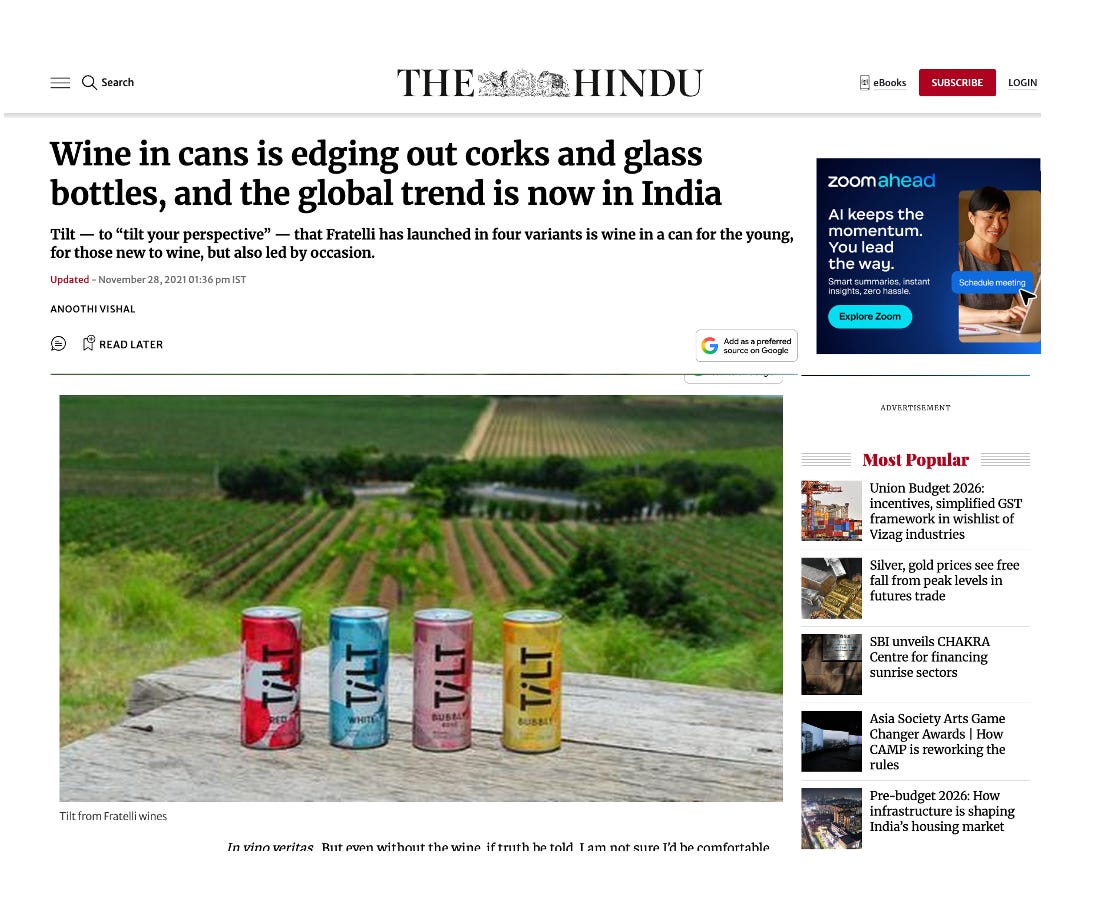
If I had to back a horse, it would probably be bottles of Moscato and cans of fruit-flavoured wines that are being produced by Indian companies like Sula and Fratelli
And, please, please, please, don’t even contemplate talking about food-and-wine pairing in India.
If we take an innovative approach to the Indian market, and with the help of the European and the earlier Australian trade deal, we can reasonably hope for an annual compound growth of 5-10%.
I’m sorry if that’s a disappointingly long way off the 12%, 16% and 24% of those pricy reports but, given the prospects everywhere else, as co-owner of Le Grand Noir, India’s biggest-selling French wine brand, I reckon it’s the kind of progress we should be very happy to get.
Perhaps not the tonic everyone hoped for, you're surely right, but it is a new toy for everyone to play with. There will be a rush to fill all of the pipelines with brand after brand after brand no doubt, but I believe after a five year or so settling in period it will represent a net positive for the EUs producers. I was having lunch with the owner of a Pomerol chateau of minor size and major reputation who welcomed the news very warmly, imagining a lot of blue sky in that market for her, and I think (for a lot of luxury brands) she's correct that the iconic labels have a new market to work with.
Love this perspective! Your analysis skillfully cuts through the hype, providing a much-needed data-driven reality check. It's cruchial to look beyond projections and consider the actual market dynamics. Thank you for this insightful contribution.